One Of the Most Valuable Lending Opportunities Available to Medical Professionals
When doctors start exploring property ownership, most focus on three things:
- Deposit size
- Borrowing capacity
- Interest rates
What many don’t realise is that one of the biggest upfront costs associated with buying property may not apply to them at all.
Through selected lenders, eligible medical professionals may be able to access Lenders Mortgage Insurance (LMI) waiver programs, potentially saving thousands of dollars when purchasing a property.
What Is LMI?
Lenders Mortgage Insurance is typically charged when a borrower has less than a 20% deposit.
A common misconception is that LMI protects the borrower.
In reality, LMI protects the lender if the loan defaults. The borrower pays the premium but receives no direct insurance benefit.
Depending on the property value, loan amount and deposit size, LMI can add a significant cost to a property purchase.
Why Do Some Lenders Offer LMI Waivers to Doctors?
Many lenders view medical professionals as lower-risk borrowers due to:
- Strong earning potential
- Stable career pathways
- Ongoing demand for healthcare services
- Professional registration requirements
As a result, selected lenders have created specialised policies for eligible healthcare professionals.
These policies may include the ability to borrow above 80% LVR without paying LMI.
Who May Be Eligible?
While policies vary considerably between lenders, eligible professions may include:
- Doctors
- Interns
- Residents
- Registrars
- General Practitioners
- Specialists
- Surgeons
- Other Healthcare Professionals
Depending on lender policy, eligibility may also extend to:
- Dentists
- Veterinarians
- Pharmacists
- Physiotherapists
- Optometrists
- Other approved healthcare professions
It’s Not Just About Your Profession
One of the biggest mistakes we see is assuming all doctors automatically qualify.
Eligibility can depend on:
- Professional Registration
Many lenders require current registration with AHPRA or another recognised professional body.
- Income
Some lenders apply minimum income thresholds depending on profession and policy.
- Employment Structure
Locum, contractor, PAYG and private practice arrangements may be assessed differently.
Property Purpose
Criteria may differ between:
- Owner-occupied properties
- Investment properties
- Refinancing
Why Lender Choice Matters
This is where previous discussions in our series become important.
Just as lenders assess:
- Overtime differently
- Locum income differently
- Allowances differently
They also approach LMI waivers differently.
One lender may offer an LMI waiver for a particular profession while another may not.
One lender may support a higher loan-to-value ratio than another.
One lender may have different income or registration requirements.
That’s why understanding your options before submitting an application can be valuable.
The Bigger Opportunity
Many doctors view an LMI waiver simply as a cost saving.
While savings can certainly be meaningful, the real benefit is often flexibility.
An LMI waiver may allow eligible borrowers to:
- Enter the market earlier
- Retain more savings
- Preserve emergency funds
- Reduce upfront purchase costs
- Keep capital available for future opportunities
The long-term value often extends beyond the premium itself.
The Bottom Line
LMI waivers remain one of the most valuable lending benefits available to eligible medical professionals.
However, there is no universal policy.
Eligibility depends on:
- Profession
- Registration
- Income
- Employment structure
- Property type
- Lender policy
Understanding those differences before applying can potentially save both time and money.
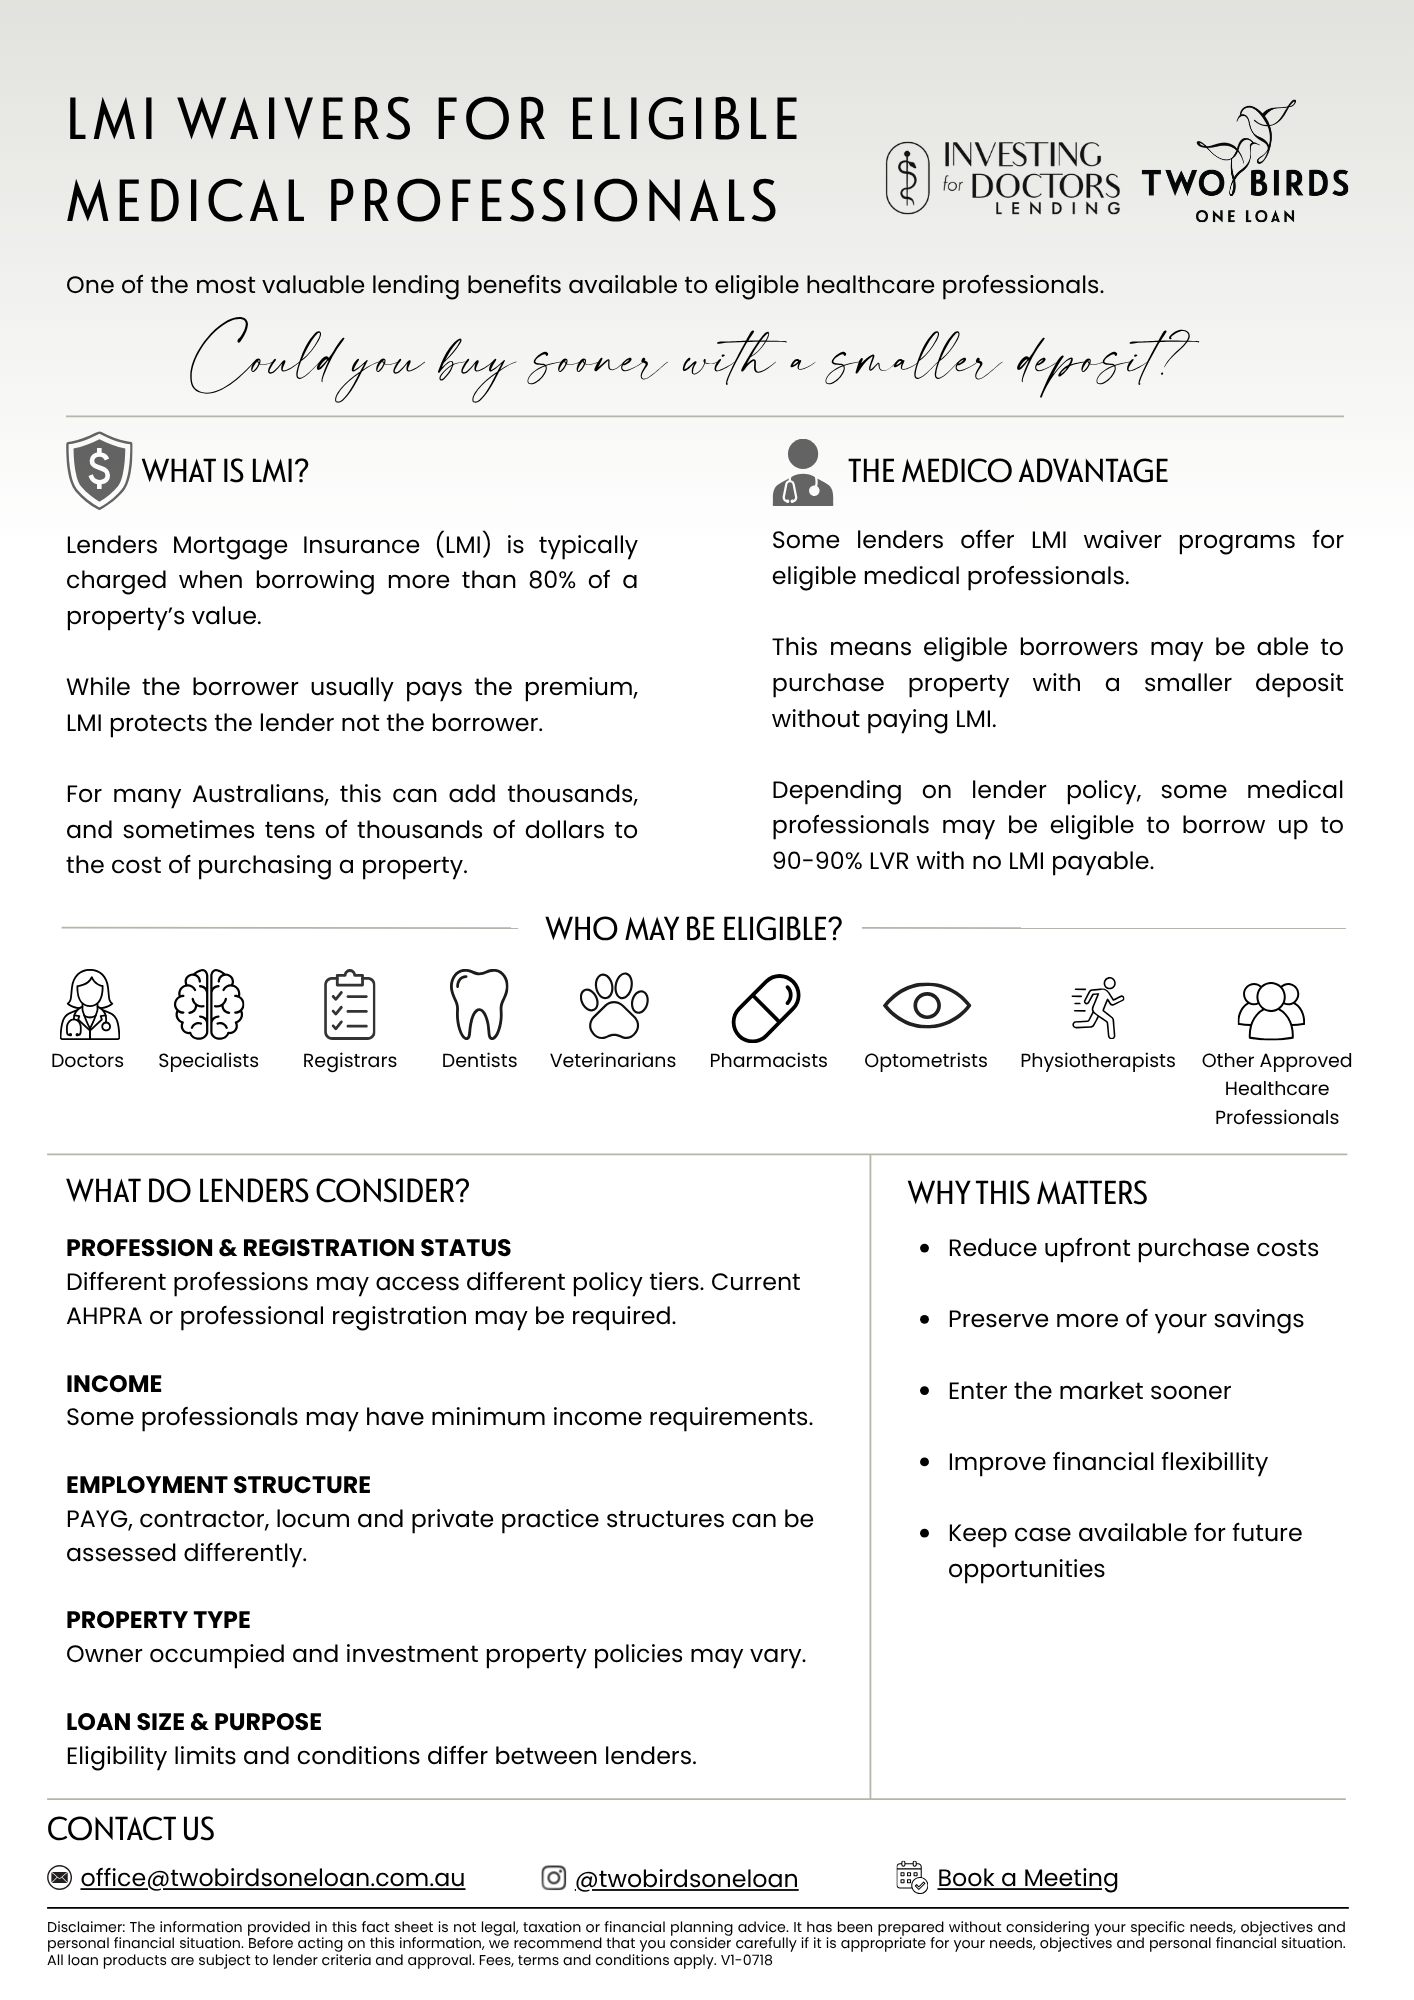
Check out our LMI Finance Fact Sheet here.
Ready To Explore Your Options?
At Two Birds One Loan, we help doctors and healthcare professionals navigate lender policies, borrowing strategies and lending opportunities tailored to their circumstances.
Whether you’re purchasing your first home, upgrading, investing or refinancing, we’d love to help.
Book Your Complimentary Lending Strategy Session. Click here to book a meeting.